

Executive summary
Public Packages Holdings Berhad (PPHB) is an established Malaysian paper packaging manufacturer (converter) with seven plants and approximately USD 40m of packaging sales at a solid 18-20% EBIT margin. It also owns a hotel (!) in Penang that opened in 2019 and is now a profitable operation contributing 20% of group EBIT.
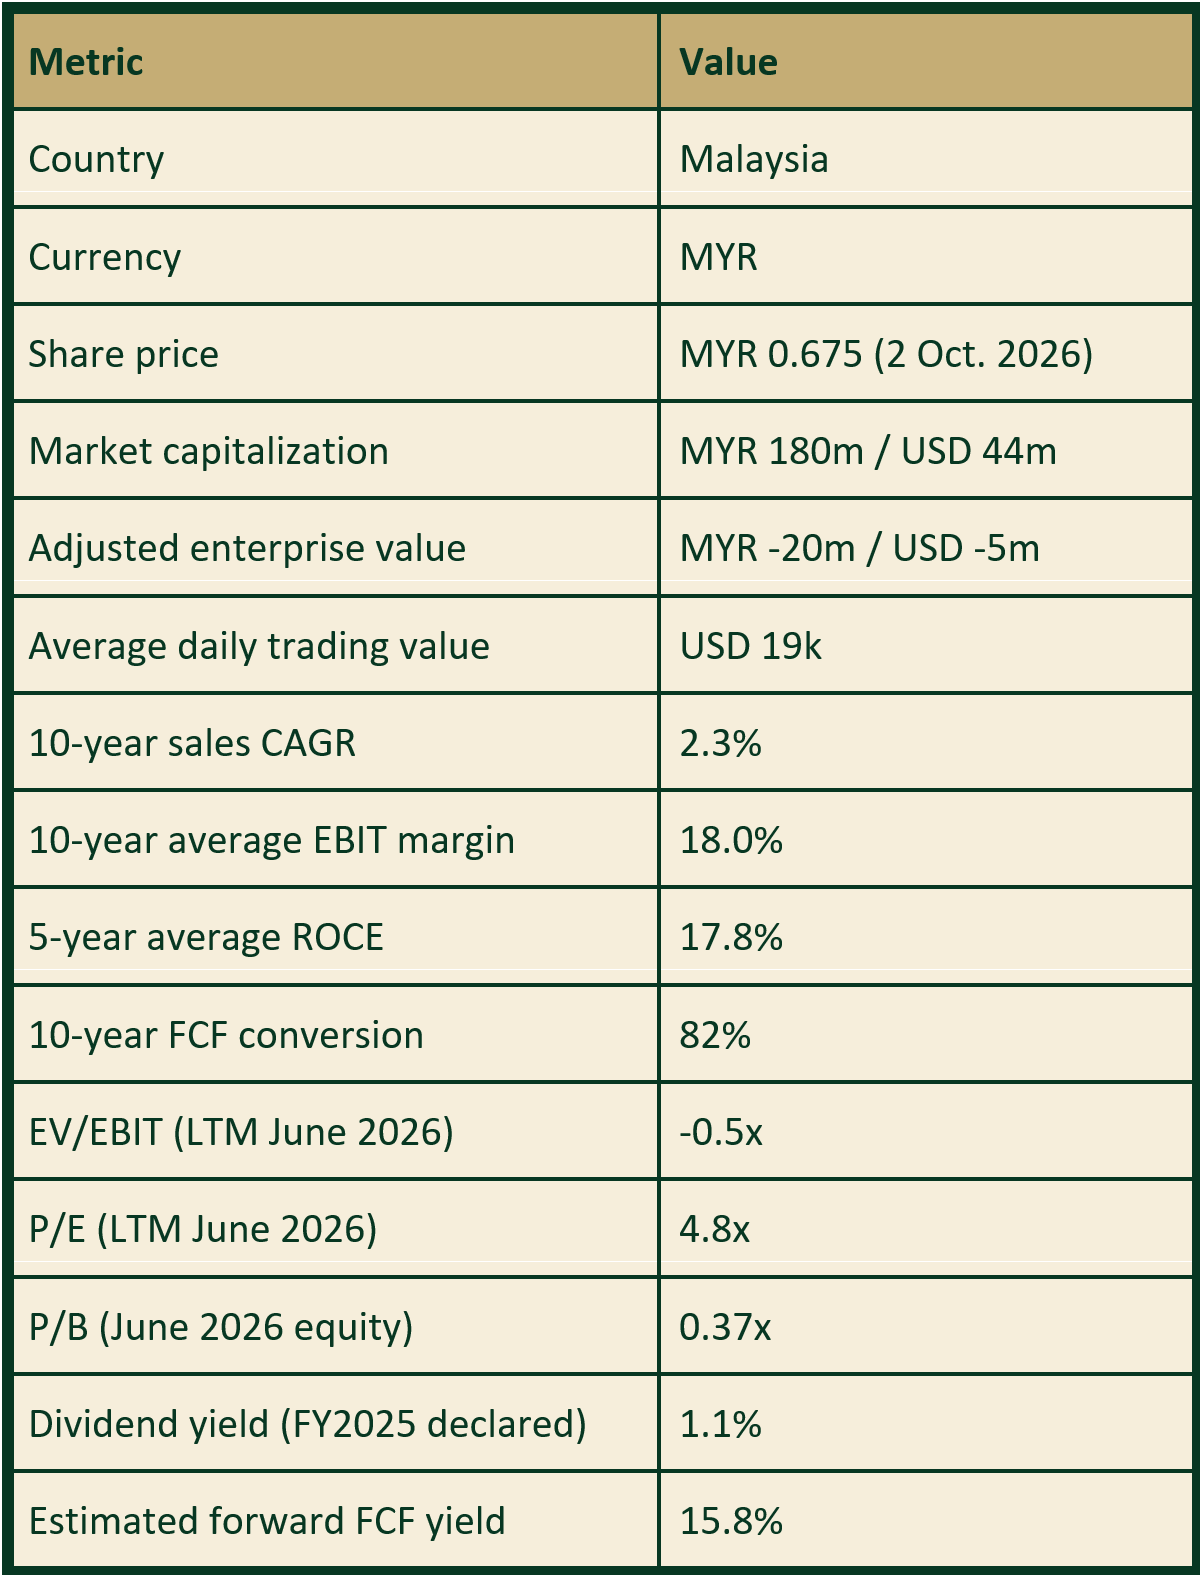
PPHB is overcapitalized (investment property and net financial assets are 159% of market cap), has solid operating returns (>20% pre-tax ROCE) and trades at an unusually low valuation (4.8x LTM P/E, 0.37x P/B, 16% forward free cash flow yield).
We are shareholders in the company.
This is one where I am practicing some light-touch activism. With solid packaging and hotel operations and a severely overcapitalized balance sheet, the current dividend is just too low. For 2025, PPHB paid out MYR 0.0075 per share (MYR 2m in aggregate), a measly 6% pay-out ratio on MYR 34m of normalized net income. I have proposed to the company that they should institute a policy of paying out at least 50% of net income (adjusted for any unusual items). That would increase the dividend yield from 1% to 9%.
Snapshot
Business and competitive position
PPHB makes corrugated cartons, offset-printed gift and display boxes, and other packing materials. Seven plants and design capabilities support local delivery and repeat customer specifications. Manufacturing generated MYR 168m of FY2025 revenue, trading MYR 8m and the Prestige Hotel in Penang MYR 23m. Property holdings, financial investments and two 50%-owned joint ventures add other sources of earnings.
About 94% of sales were to Malaysian customers. No customer exceeded 10% of revenue, although two represented 30% of trade receivables. Local sales can still depend on customers’ export demand for their end products.
Design, print quality and dependable delivery help retain orders. Box-Pak, HPP, Master-Pack and integrated paper and packaging groups provide substantial competition. The plant network and customer relationships support the franchise, but the disclosures offer little evidence of exclusive contracts or durable pricing power. Paper, labour, energy and machinery utilisation remain important drivers of profitability.
Long-term financial development

Over twenty years, sales rose from MYR 123m in FY2005 to MYR 200m in FY2025, a 20-year CAGR of 2.5%. Growth has been modest and uneven.
Profitability improved much more than sales. Consolidated gross margin has increased from 20-25% in the early years to ~40% today. To understand this, we need to look at the packaging and hotel/hospitality segments separately. PPHB broke ground on the Prestige Hotel in Penang in 2016 (on land already owned by the group) and opened the hotel in 2019 (just in time for Covid…). After three years of start-up and Covid losses the hotel became profitable in 2022:

In 2025 the hotel/hospitality segment generated a 32% adjusted EBIT margin which skews the group margin. However, the packaging business in isolation has also improved its profitability from 12-14% margin to 18-20%. Management attributes the improvement partly to broader printing and packaging capabilities, automation and production efficiency.

PPHB has an established factory network that has become more efficient and selective, with broader capabilities and a more profitable earnings mix. Historical reports describe a progression from cartons toward customized packaging, graphic and structural design, displays, and material-management/storage/fulfilment services, with an integrated printing line installed in 2022.
The long-term history of operating capital employed and pre-tax ROCE is also skewed by the hotel construction from 2016-2019 (increased assets), the hotel losses in 2019-2021 (muted ROCE) and the turn to significant hotel profitability from 2022 (jump in ROCE). Nevertheless, PPHB has a very solid track record of improving and attractive levels of ROCE:

The asset impact of the hotel construction can be seen clearly in the CapEx segment disclosures:

Cash generation and quality
I always want to look at a company’s long-term track record of converting net income to after-tax free cash flow as a quality measure. PPHB’s rolling 5-year conversion is again impacted by the 2016-2019 hotel construction:

We don’t have the information to isolate the packaging business, but on a group level PPHB converted a strong 99% of its latest rolling 5-year net income to free cash flow.
Capital allocation and governance
The Koay family has substantial influence through its 41% stake (direct holdings and ownership vehicles).
Cash dividends paid over FY2019–25 totaled MYR 3.6m, only 2% (!) of available free cash flow. The FY2025 dividend (paid in 2026) of MYR 0.0075 per share yields 1.1% at MYR 0.675. I believe retaining excess capital in securities and property is a major reason for the low valuation.
Valuation and financial assets
At MYR 0.675, market capitalization is MYR 180m (USD 44m). After adjusting for non-recurring income, the LTM P/E is 4.8x and P/B is 0.37x. These ratios reflect both the operating businesses and the financial and property portfolios (but exclude revaluation gains).
The amount of non-operating assets as of 30 June 2026 is striking:

As usual we only credit 70% of non-operating assets in our adjusted enterprise value, recognizing that surplus capital may remain on the balance sheet. Even on that basis, adjusted EV is negative MYR 20m. Over the last 20 years, the EV on that basis has mostly been positive and the EV/EBIT multiple has averaged 4-5x vs. the current negative multiple. LTM P/E has averaged 6x over the last 20 years:

Our first forecast year estimates MYR 28m of after-tax free cash flow (vs. the 5-year historical average of 33m), ~87% of after-tax operating profit and a 16% yield on market capitalization.
With these small, illiquid opportunities it is difficult to talk about public valuation comparables (they all have different characteristics with family control, capital allocation policies and other idiosyncrasies), but for comparison HPP Holdings (Malaysia ticker 0228; high product overlap with PPHB) trades at 14x EV/EBIT, 20x P/E and 0.85x P/B (using the same definitions as for PPHB).
Base Case Return Potential
If we assume 2% sales growth, unchanged EBIT margin from the operating businesses (packaging and hotel) and that – through internal and/or external factors – the company eventually starts to distribute 50% of net income and then trades at a 5% dividend yield, we get the following implied future multiples and annualized returns:

Given the rock-solid balance sheet and attractive operating business, waiting for improved capital allocation strikes us as a solid risk/reward proposition.
Key Risks
Packaging volumes could fall as industrial demand weakens, or margins could be hit by input costs; hotel earnings add exposure to Penang travel demand.
Conservative capital allocation could continue for years, leaving a low dividend yield despite substantial accumulated financial assets.
Investment losses, property valuation changes, joint venture obligations and related-party decisions could weaken the value available to minority shareholders.
Sources
Koyfin and Bursa Malaysia company filings; Author calculations.
Disclaimer
This publication is for information and discussion only. It is not investment advice or a recommendation to buy, hold or sell any security and does not consider your financial circumstances. Do your own due diligence and seek independent professional advice where appropriate.
I may own securities discussed and may buy, add to, reduce or sell positions at any time without notifying readers, subject to applicable disclosure requirements. My interests may differ from yours. Opinions and estimates may change without notice; I do not undertake to provide trading updates.
Information is believed reliable but may contain errors or omissions. Forecasts are uncertain, past performance does not predict future returns, and investments can lose some or all of their value. Small and micro-cap shares may be illiquid, and currency movements can affect returns.
A 6% payout explains most of the discount for me. With investment property and net financial assets at 159% of market cap, every ringgit PPHB keeps gets priced well under face, so the 50% ask is the catalyst. I'd check that a 16% forward FCF yield still covers a 9% dividend in a weak carton year.
Negative EV on a business converting 99% of earnings to cash is hard to ignore, and it's good to see the Penang hotel earning its keep. With the Koay family at 41%, did management say anything when you proposed the 50% payout policy, or is the real lever just waiting for the next generation to want the cash?